

The U.S. House voted November 11, 2026, to double the funding fee on VA loan assumptions. If the proposal becomes law, buyers taking over an existing VA mortgage could face a higher fee at closing.
But the increase hasn't been enacted. As of November 19, the VA assumption funding fee remains 0.5% of the outstanding loan balance. The House-passed bill would raise it to 1%.
Meanwhile, a Jacksonville home is being advertised with an assumable VA mortgage at 2.87% interest. That's the kind of number that makes someone look twice, especially when comparing it with the cost of financing a home today.
You aren't automatically borrowing the home's full purchase price at that rate. You're taking over whatever the seller still owes.
The difference between that balance and the agreed purchase price may require substantial cash or separate financing. And that's before accounting for the assumption fee, closing expenses and approval requirements.
1. How much of the Jacksonville home's price can you actually assume?
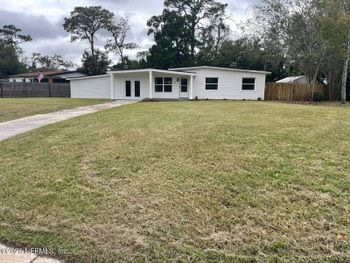
Consider 6107 Black Stallion Drive in Jacksonville's Winchester Ridge community.
The three-bedroom home was listed as active when checked November 19. Its realMLS listing, number 2160106, advertises an assumable VA mortgage with a 2.87% interest rate.
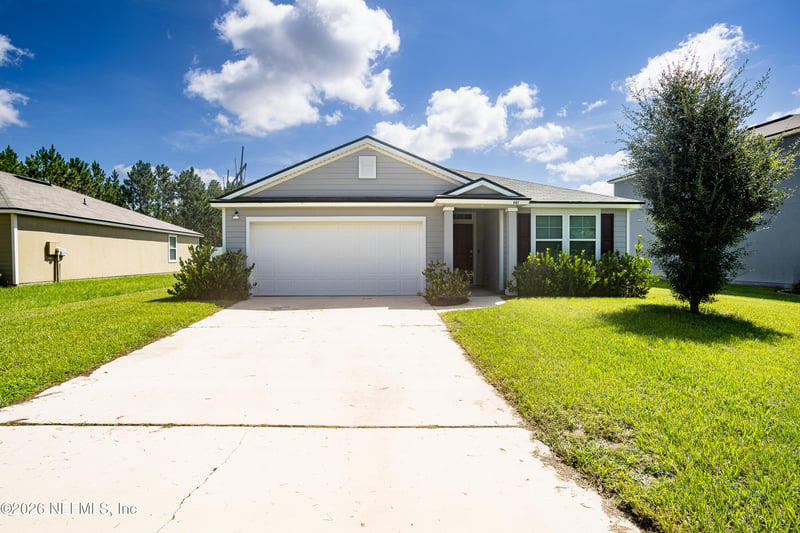
6107 Black Stallion Drive, Jacksonville, FL 32234. View the current listing and details. Photo: FLORIDA HOMES REALTY & MTG LLC / realMLS, MLS #2160106.
What the public listing doesn't establish is how much remains on the mortgage, how many years are left or what the buyer's actual payment would be.
Suppose the seller owes considerably less than the agreed sale price. An approved buyer could assume that remaining debt at the existing mortgage terms, but the difference still has to be paid.
That's the equity gap, and it can change the entire calculation.
A buyer might have cash available to cover it or explore additional financing, subject to lender approval. Neither should be assumed before the numbers are known.
This is also where the familiar no-down-payment benefit associated with a new VA purchase loan can create confusion. It doesn't mean a buyer can assume an existing mortgage without paying the difference between the loan balance and the purchase price.
For the Black Stallion Drive listing, confirm the loan details with the seller and servicer, then compare them with buyer-specific estimates of taxes, insurance and association costs:
- Remaining loan balance: How much existing debt would transfer to the buyer?
- Loan terms: Is the advertised rate accurate, how much time remains, and what principal-and-interest payment would carry over?
- Cash requirement: How much of the agreed price isn't covered by the assumed mortgage, and how will the buyer pay it?
- Total housing payment: What will property taxes, homeowners insurance, applicable association dues and any other required costs add? Obtain estimates from the relevant tax office, insurance agent and association rather than assuming the seller's bills or existing escrow amounts will carry over unchanged.
Without that information, a 2.87% advertisement can't establish the buyer's actual savings or affordability.
2. Is the VA loan assumption funding fee 0.5% or 1%?
On November 11, the House passed H.R. 9237, the Take Care of America's Veterans Act, by voice vote.
Section 104(b) of the House-amended legislation would raise the funding fee for VA loan assumptions from 0.5% to 1.0%.
The bill also proposes increasing the separate Interest Rate Reduction Refinance Loan (IRRRL) funding fee from 0.5% to 1.42%. An IRRRL is a refinancing transaction, not an assumption fee charged on top of the first increase.
Neither change was enacted as of November 19.
The VA's official funding-fee schedule, updated October 5 and checked November 19, still lists 0.5% for assumptions.
That fee is based on the outstanding mortgage balance being assumed, not the home's selling price. When applicable, the assumption funding fee must be paid at the time of transfer and cannot be added to the mortgage being assumed.
Some buyers qualify for funding-fee exemptions. Ask the servicer to confirm the buyer's eligibility using the required documentation; the seller's previous exemption status doesn't automatically carry over.
And the funding fee isn't the only closing expense.
Applicable processing charges, title and recording costs, prepaid expenses and other transaction charges may also affect the amount due. Ask the servicer and closing professionals for an itemized estimate instead of treating 0.5% as the total cost of the assumption.
Those itemized charges belong alongside the equity gap when calculating the cash needed at closing.
Home904's guide to the hidden costs of buying a first home in Northeast Florida explains why loan charges, prepaid expenses and ongoing ownership costs need to be considered separately.
3. Can a non-Veteran assume a VA loan, and who approves it?
A buyer doesn't have to be a Veteran. The VA Home Loan Buyer's Guide explains that a qualified non-Veteran can assume a VA-backed mortgage.
The existing loan servicer must approve the assumption, and some transactions also require VA approval. The servicer generally reviews the prospective buyer's income and credit to determine whether the buyer can afford the mortgage obligation.
Before signing, ask the servicer for its application requirements, document checklist and expected processing schedule. Then make sure the purchase contract addresses assumption approval and the closing timeline.
If approval takes longer than expected, the buyer's and seller's rights depend on the contract's actual terms. Neither an advertised rate nor an ordinary mortgage preapproval guarantees that an assumption will close by a particular date.
Home904's VA assumable homes for sale search can help buyers find other Northeast Florida listings advertising this possibility.
The search matches VA-assumption language in active listing descriptions. It may miss homes without those phrases, and a matching listing doesn't verify the loan terms, eligibility or servicer approval.
4. What happens to the Veteran seller's VA entitlement?
Even when the buyer qualifies, the seller has a separate reason to examine the transaction carefully.
A Veteran's VA home-loan entitlement is the benefit supporting the government's guaranty of the mortgage. That entitlement can remain committed to the existing loan after someone else assumes it.
A qualified Veteran buyer with sufficient entitlement may be able to substitute their entitlement for the seller's through the approved process. That can allow the original Veteran's entitlement to be restored.
If a qualified non-Veteran assumes the mortgage, the seller's entitlement generally remains tied to the loan.
This matters when the seller wants to use VA financing for another home. An assumption that works for the buyer may leave the seller with less entitlement available for the next purchase.
There's also a distinction between release from liability and restoration of entitlement.
Release from liability concerns the original borrower's continuing responsibility for the mortgage. Restoration of entitlement concerns the availability of the seller's VA home-loan benefit.
One doesn't automatically establish the other.
A Veteran seller should ask the servicer and VA what approvals and written documentation are required for each. A seller who needs entitlement restored may consider an offer from an eligible Veteran buyer differently from one involving a non-Veteran, even when both can qualify financially.
Before making an offer, look past the advertised rate
If you've found a Jacksonville or Northeast Florida home advertising an assumable VA loan, send Susie Takara the listing through Home904's complimentary buyer research service. She can help compare the property's advertised features with available information and organize the loan-balance, cash-to-close, contract-timing and entitlement questions for the listing side, lender and servicer before you make an offer.